A Gentle Reminder | Buying Insurance Is Only the Beginning
We service our cars, renovate our homes and upgrade our phones regularly.
Yet many of us buy insurance and then may not look at it properly for ten years.
It is not because we do not care. Insurance simply is not most people’s area of expertise.
We all have areas we know well. In our own work, we know what to pay attention to, what matters and what could go wrong.
With insurance, though, we often face “unknown unknowns”—we may not even know what we do not know.
We may know that we have a medical card, but not know:
How much medical cover can we actually use in a year? Is that limit still enough for today’s medical costs? Is there a co-payment or anything else we would need to pay ourselves? Until what age does the cover last? Does the protection we bought ten years ago still suit us today?
When we are healthy, these questions rarely feel urgent.
But when illness happens, treatment will not simply wait until next year because our cover is insufficient.
With a serious illness, complex surgery or long-term treatment, many medical expenses may arise within a short period.
That is why I have always paid close attention to the annual medical limit when reviewing medical protection.
Of course, a medical card should never be judged by one number alone. The annual medical limit, Lifetime Limit, scope of cover, co-payment, renewal conditions, exclusions and the structure of the whole policy all need to be understood together.
The important question is not: “How many insurance policies do I have?”
It is: “If something really happens, will my current protection give my family and me enough choices?”
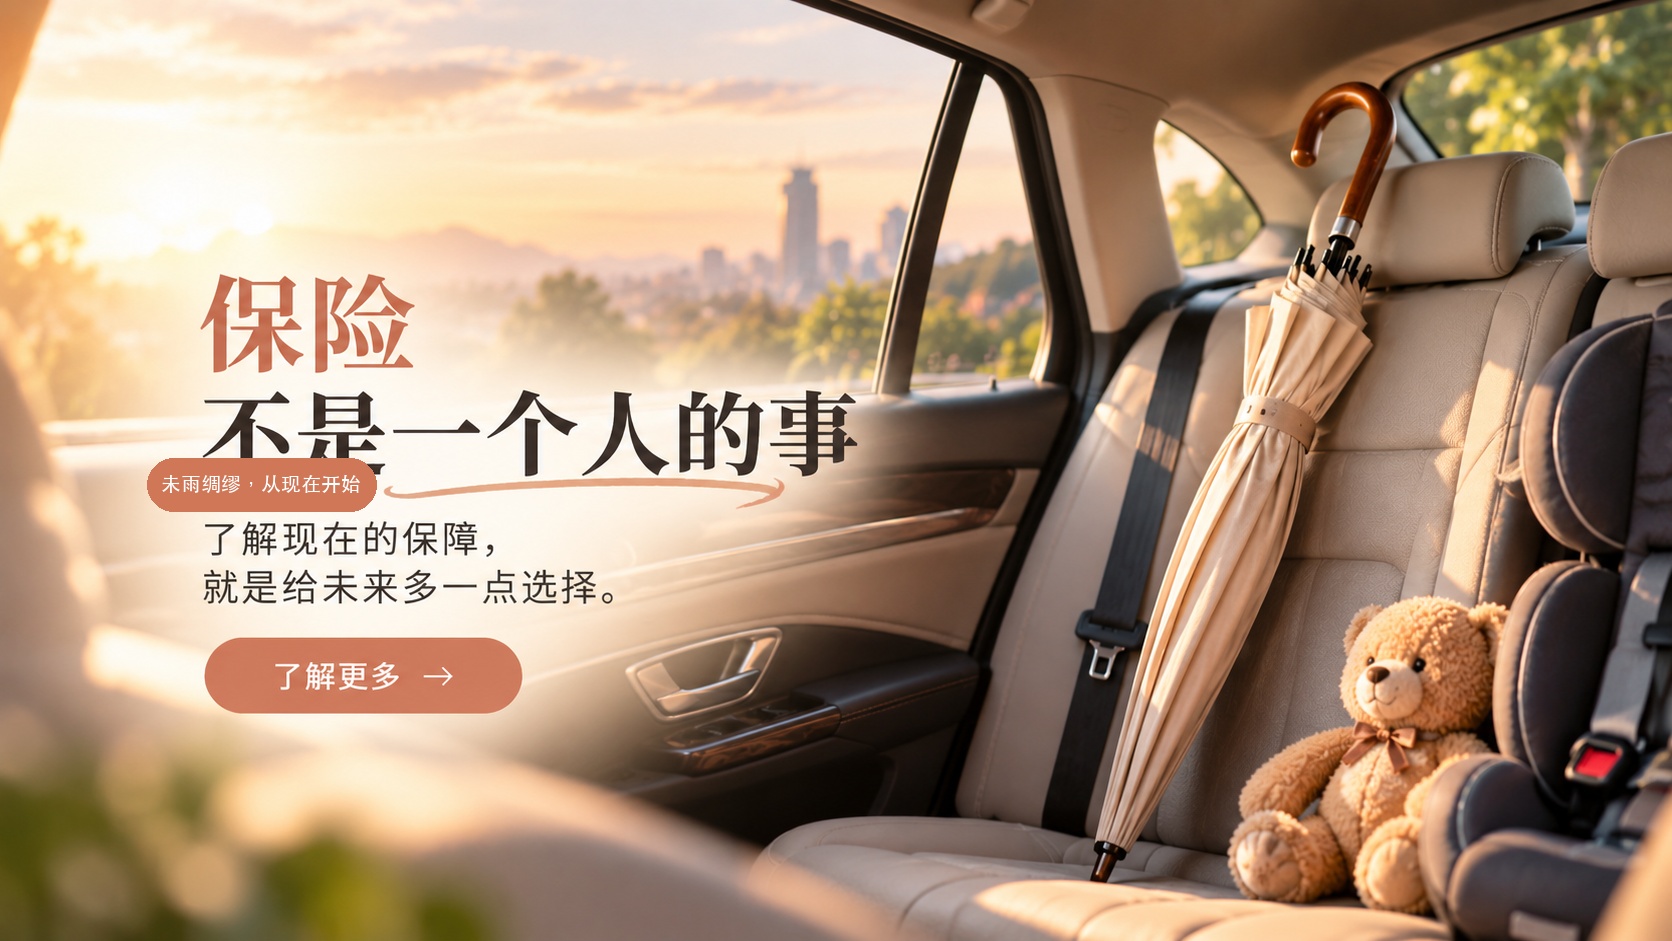
Insurance is the umbrella we keep in the car
There is a simple comparison I like to use.
We keep an umbrella in the car not because it will definitely rain today, but because we know it may rain one day.
If we are alone in the car and get wet, perhaps we can grit our teeth and get through it.
But if our partner, children and other people we love are with us, we naturally want to be able to protect them.
Insurance is much the same. It has never been just about one person. It is about a whole family.
When one person becomes ill, the consequences often extend beyond that person.
Someone may need to put work on hold to provide care. Someone may worry about medical bills. Someone may carry an enormous emotional burden. A family’s plans may change because of an illness.
That is why I often say: when one person falls ill, the whole family may become “invisible patients”.
Good protection cannot promise a life without storms. What it can do, when a storm comes, is give a family a little more choice, a little less helplessness and the strength to get back on its feet.
Why prepare your insurance while you are healthy?
Insurance has one distinctive feature: you cannot be sure you will be able to buy it only when you need it.
When we are healthy, we usually feel we will not need insurance any time soon.
But if our health has changed and we want to increase our cover, the outcome depends on the insurer’s underwriting assessment and the protection applied for. We may face a higher premium, exclusions, postponed acceptance or even be declined cover.
Preparing ahead is not pessimism. It means putting what we can in place while we still have choices.
You do not necessarily need more insurance
This is something I really want people to know.
After all these years working in insurance, I do not believe every policy review should end with “buy another policy”.
If your current protection is enough and its structure suits you, I will tell you: there is no need to add more.
Being professional does not mean getting someone to buy as much as possible. It means helping them understand what they already have, what they have done well, which risks remain unaddressed and whether their existing protection can help with what truly worries them.
If insurance has always been a blind spot for you, that is okay
You do not need to study insurance before coming to me. This is my area of expertise.
If you already have insurance but have never quite understood what it covers; if you are unsure whether the medical card you bought ten years ago is still enough; or if you simply want a more objective opinion but worry that asking an insurance agent will lead to a hard sell, you are welcome to talk to me.
I offer a free policy consultation: a review of your policies and a conversation about your protection.
You can bring your existing policies for me to look at. First, I will listen: What worries you? Who do you want to protect? If something unexpected happens in life, what consequence would you most want to avoid?
Only then will we look together at whether your current protection can address those risks.
If it is enough, keep it. If something is missing, we can discuss whether there is a suitable way to fill the gap.
There is no pressure, and meeting me does not mean you have to buy anything.
I believe a truly professional insurance adviser does not rush to tell you what to buy. First, they help you understand where you stand, what you fear and whether you have enough support to face a day you cannot predict.
Insurance cannot stop the storms. But before they arrive, we can have our umbrella ready.
If you would like to know whether your protection still suits you today, reach out to me. I will listen patiently, then help you make sense of your cover.
Disclaimer
This article is for educational purposes only and does not constitute financial or insurance advice. Coverage terms are subject to the policy contract. Contact Faith for personalised advice.